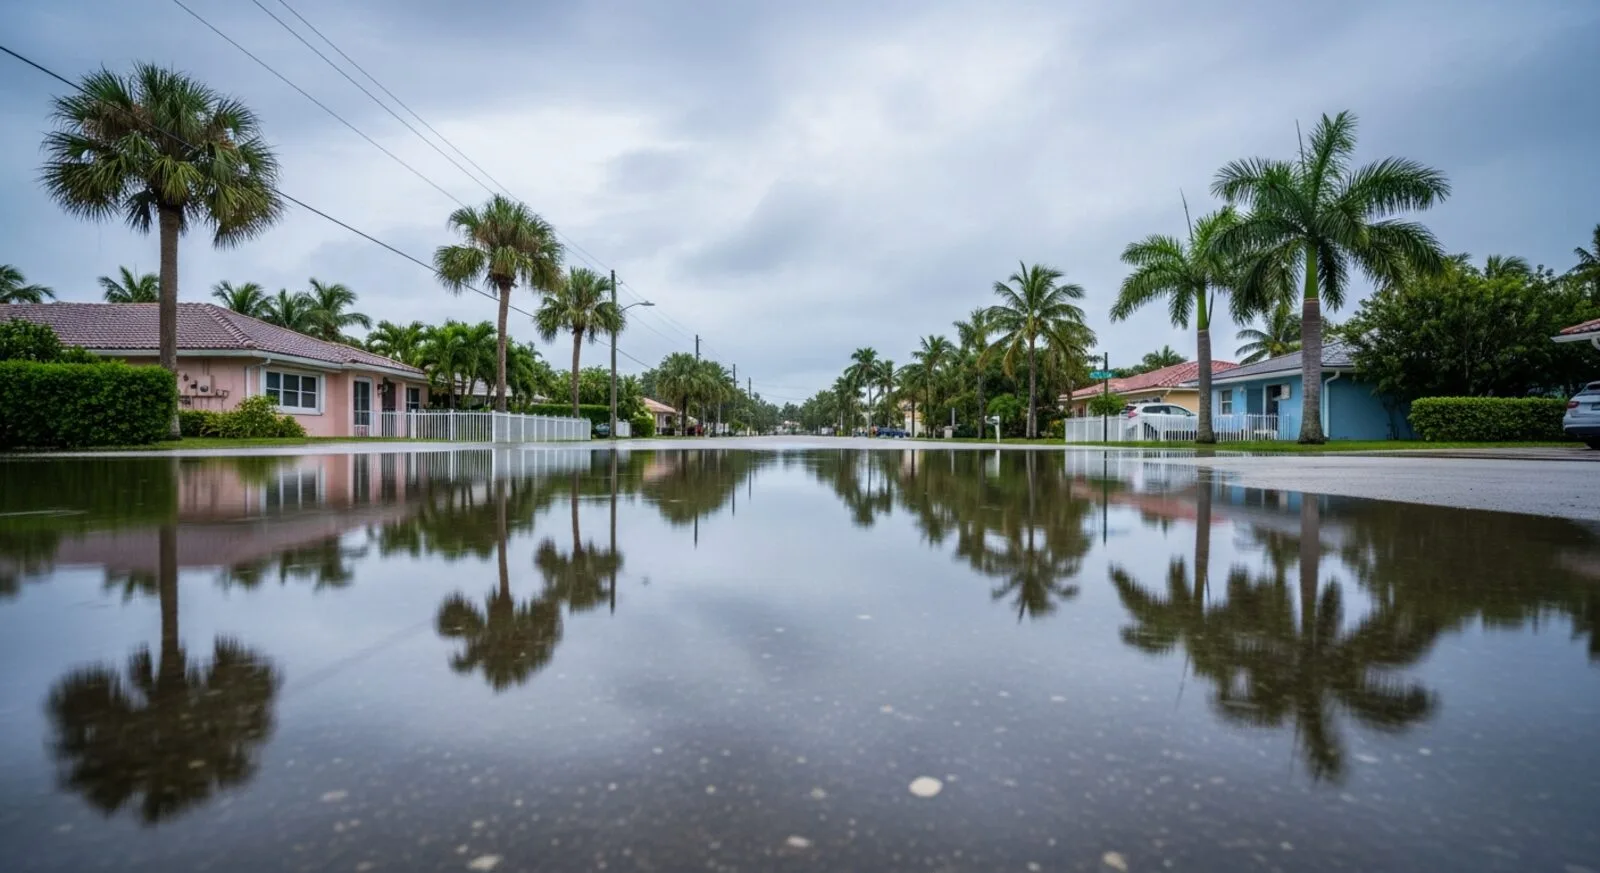
One of the most common misconceptions we hear in our Lantana office is, "my homeowners insurance covers flooding." It does not. Flood damage from rising water — whether from a hurricane storm surge, a king tide, or heavy rain that overwhelms storm drains — is excluded from every standard homeowners policy in Florida.
NFIP vs. private flood
There are two main markets for residential flood insurance: the National Flood Insurance Program (NFIP), administered by FEMA, and the growing private flood market. NFIP coverage is capped at $250,000 for the building and $100,000 for contents. Private flood policies often offer higher limits, replacement cost on contents, additional living expense coverage, and shorter waiting periods.
Who needs flood insurance?
- Homeowners in FEMA designated high-risk zones (AE, VE, etc.) with a federally backed mortgage are required to carry it.
- More than 25% of NFIP claims come from properties outside the high-risk zones.
- Renters can purchase contents-only flood policies, often for less than $200 per year.
- Condo unit owners should review their HOA master flood policy and fill the gaps with an HO-6 flood policy.
Plan ahead — there is a waiting period
Most flood policies have a 30-day waiting period before coverage takes effect. You cannot buy a policy the day before a hurricane and expect it to pay. Bind your coverage at the start of the season, not when the cone is pointed at us.
Talk to a Lantana independent agent
Independent agents who actually shop the market. B & B Insurance Agency has served South Florida from our Lantana office since 1998. We'll find the carrier that fits your life — not the other way around. Talk to an agent.
Have a question about this topic?
Our experienced agents are happy to help — no pressure, just straight answers.