TL;DR: A standard Florida BOP covers your building, business personal property, and general liability, but it routinely excludes flood, professional liability, equipment breakdown, employment practices liability, and cyber liability. Each gap can produce a five- or six-figure loss with no policy to respond. Review all five before your next renewal.
A Business Owners Policy (BOP) is designed for small to mid-size businesses. It bundles commercial property and general liability into one policy at a lower combined cost than buying each separately. That convenience is real, but the bundled form also hides what it leaves out.
Florida businesses face above-average exposure on several fronts: hurricane-driven flooding, a litigious employment environment, and a growing reliance on digital systems. The five coverages below address those exposures directly.
1. Flood Damage to Your Business Property
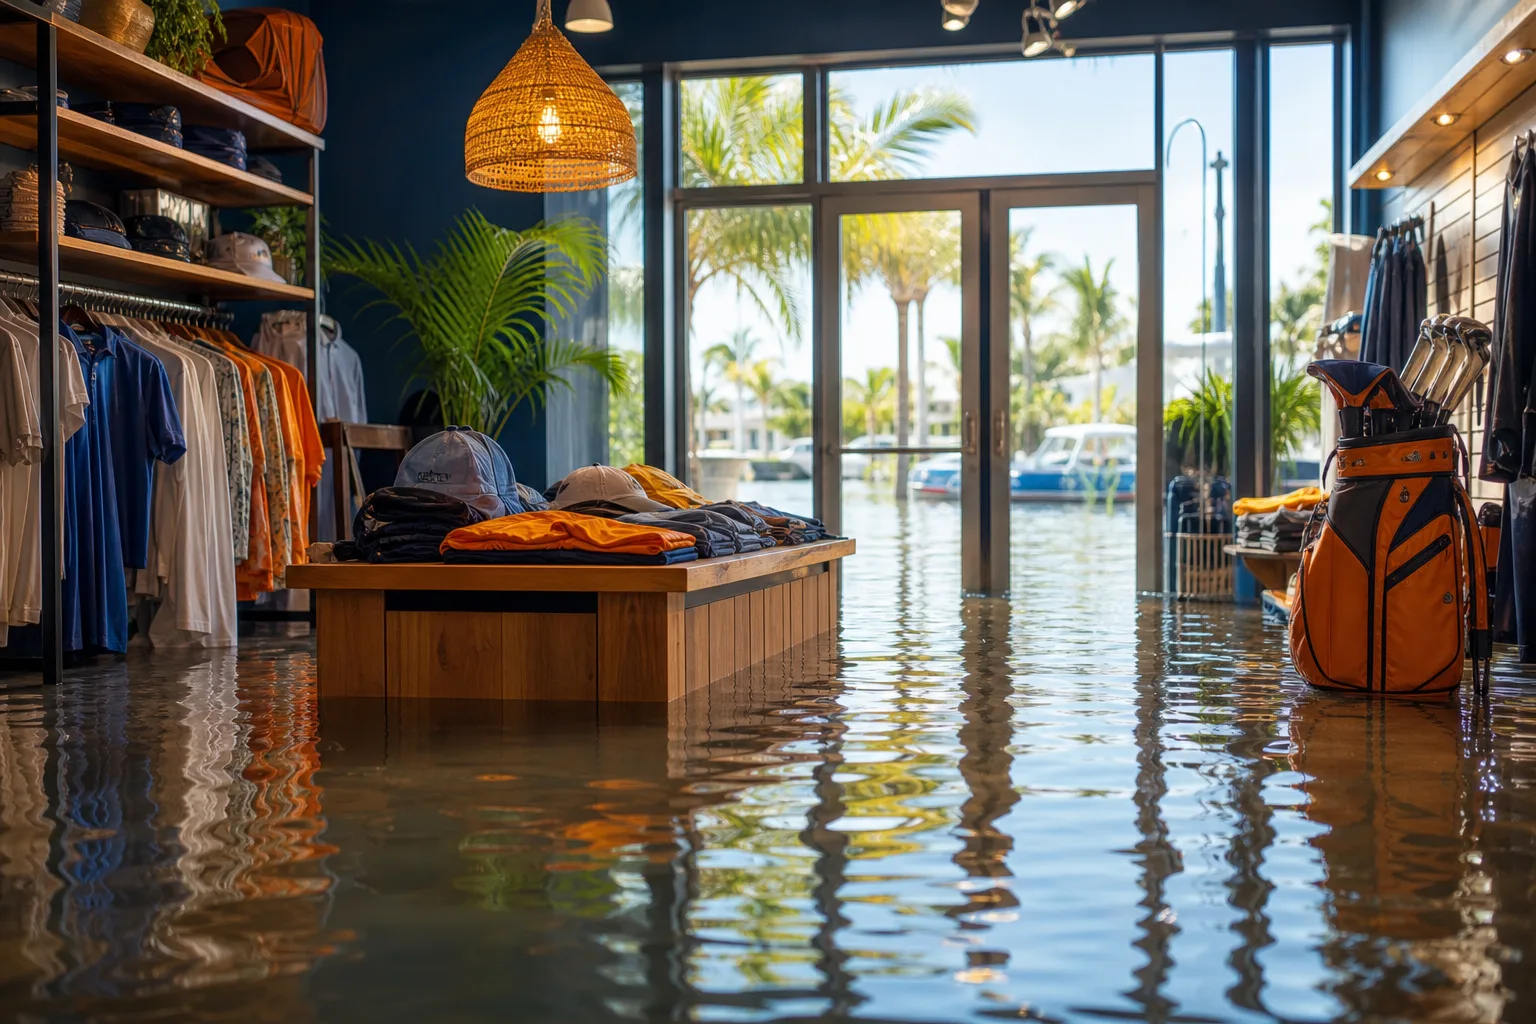
Your BOP's commercial property section covers wind, fire, theft, and most named perils. It does not cover flood. That distinction matters enormously in Palm Beach County, where storm surge and heavy rain can inundate a ground-floor retail space or warehouse even when a hurricane makes landfall well north of you.
Flood coverage for a commercial property is available through the National Flood Insurance Program (NFIP) or through private flood carriers. Building coverage and business personal property (contents) are separate limits, so confirm you have both.
Scenario: A Lantana gift shop carries $80,000 in inventory. Tropical Storm Eta drops 12 inches of rain and floods the shop with 18 inches of water. The BOP pays nothing for inventory or the damaged display cases. An NFIP commercial contents policy would have responded.
If your business occupies a leased space, your landlord's flood policy covers the building structure only. Your contents are your responsibility.
2. Professional Liability (Errors and Omissions)
General liability, which is included in your BOP, covers bodily injury and property damage you cause to others. It does not cover a claim that you gave bad advice, made a professional error, or failed to deliver a promised service.
Professional liability (also called E&O) fills that gap. It applies to consultants, accountants, real estate agents, insurance agents, IT professionals, marketing firms, and any business that charges clients for expertise or a specific outcome.
The Insurance Information Institute notes that professional liability claims often arise from contract disputes and perceived negligence, not physical accidents. A general liability policy will not respond to those allegations.
Scenario: A bookkeeping firm files a client's quarterly taxes incorrectly, resulting in a $30,000 IRS penalty. The client sues for the penalty plus legal fees. The BOP's liability section is silent. E&O coverage would apply.
See professional liability insurance for more on how this coverage works.
3. Equipment Breakdown
Commercial property in a BOP covers equipment damaged by a covered peril such as fire or theft. It does not cover mechanical or electrical breakdown from within the equipment itself.
Equipment breakdown coverage (sometimes called boiler and machinery coverage) pays for repair or replacement of HVAC systems, commercial refrigeration, compressors, electrical panels, and production machinery when they fail from internal causes.
For a Florida business, HVAC failure during summer is not hypothetical. A restaurant that loses refrigeration on a Friday afternoon faces spoiled inventory, a weekend closure, and potential health department involvement.
Diagnostic check:
- List every piece of equipment your business cannot operate without for more than 24 hours.
- Ask your BOP carrier whether breakdown from internal mechanical failure is covered or excluded.
- If excluded, request an equipment breakdown endorsement or standalone policy.
Some BOP forms include a limited equipment breakdown endorsement. Read the sublimit carefully; it may not cover full replacement cost.
Protect the business you've built. Talk to our business team
4. Employment Practices Liability (EPLI)
EPLI covers claims from employees alleging wrongful termination, discrimination, harassment, or retaliation. Your BOP's general liability section explicitly excludes employment-related claims.
Florida is an at-will employment state, but that does not prevent claims. The U.S. Equal Employment Opportunity Commission (EEOC) reports that small businesses face a meaningful share of workplace discrimination charges each year. Defense costs alone, even for meritless claims, can reach tens of thousands of dollars.
EPLI can be added as an endorsement to some BOPs or purchased as a standalone policy. It typically covers defense costs, settlements, and judgments.
Scenario: A five-person landscaping company in Boynton Beach terminates an employee. The employee files an EEOC complaint alleging age discrimination. Even if the claim is unfounded, the employer spends $18,000 on legal defense. EPLI would cover those defense costs.
The coverage is especially relevant if your business is growing and adding employees for the first time.
5. Cyber Liability
A standard BOP was designed before most businesses stored customer data digitally or accepted electronic payments. It does not cover costs from a data breach, ransomware attack, or network interruption.
Cyber liability coverage pays for notification costs (which Florida law requires under Section 501.171, Florida Statutes), credit monitoring for affected customers, forensic investigation, regulatory fines, and business interruption caused by a network outage.
Small businesses are common targets precisely because they often lack dedicated IT security staff. A point-of-sale breach at a small retailer or a phishing attack on a contractor's email account can trigger notification obligations to hundreds of customers.
Decision table for cyber coverage:
| Your business collects or stores... | Cyber coverage priority |
|---|---|
| Customer payment card data | High |
| Patient or health information | High (HIPAA exposure) |
| Employee Social Security numbers | High |
| Only cash transactions, no digital records | Lower, but network interruption may still apply |
Cyber endorsements are available on some BOPs; standalone cyber policies offer broader limits and more complete coverage.
Bottom Line
A BOP is a solid foundation, not a complete solution. Flood, professional liability, equipment breakdown, EPLI, and cyber liability each address a real risk that the standard form excludes. The right combination depends on your industry, headcount, and how your business operates.
As an independent agency, B & B Insurance Agency shops multiple carriers to find the coverage combination that fits your business, not a generic package. If you want a side-by-side review of what your current BOP covers and what it skips, reach out for a free quote.
You may also want to review commercial auto insurance and workers' compensation if either applies to your operation. Those are separate policies that a BOP does not include.
Protect the business you've built.
General liability, commercial auto, workers' comp, bonds, and more — bundled and shopped across carriers for South Florida businesses.
Frequently asked questions
Does a Florida BOP automatically include business interruption coverage?
Most BOPs include a business income (interruption) component that replaces lost revenue when a covered peril forces you to close. However, this coverage typically does not apply to flood losses or cyber-related shutdowns unless you have added the appropriate endorsements or separate policies.
Can a sole proprietor in Florida get a BOP?
Yes. BOPs are generally available to sole proprietors, LLCs, and small corporations that meet the carrier's eligibility criteria, usually based on revenue, square footage, and industry class. Some higher-risk trades, such as contractors, may need a separate commercial package policy instead.
How does equipment breakdown coverage differ from a home warranty?
A home warranty is a service contract that applies to residential systems. Equipment breakdown coverage is a commercial insurance product that pays repair or replacement costs for business-critical machinery when it fails from internal mechanical or electrical causes. It also typically includes spoilage coverage for perishable inventory.
Is workers' compensation included in a Florida BOP?
No. Workers' compensation is a legally separate coverage in Florida and is not part of any BOP. Florida law requires most employers with four or more employees to carry workers' comp, and construction businesses face stricter thresholds. See the Florida Division of Workers' Compensation for current requirements.
This article is general information, not legal or financial advice. Coverage depends on the terms, conditions, and exclusions of your specific policy, so talk with a licensed insurance agent about your situation.
Have a question about this topic?
Our experienced agents are happy to help — no pressure, just straight answers.