
Related coverage: Boat Insurance
TL;DR: On-water towing is sometimes included in a boat policy, sometimes sold as a separate endorsement, and sometimes excluded entirely. Check your declarations page for a towing or assistance line item, confirm any dollar sublimit, and know what a membership-based towing program covers that insurance typically doesn't.
What You Need
- Your current boat insurance declarations page
- Any membership card for a boat towing club (Sea Tow, BoatUS, or similar)
- The name of your insured vessel and agreed or actual cash value
- A basic understanding of whether your boat is kept in fresh or salt water (some towing endorsements treat offshore zones differently)
Step 1: Read Your Declarations Page for a Towing Line Item
Flip to the coverage summary section. Look for wording like "Emergency Towing and Assistance," "On-Water Assistance," or "Boat Tow." If it appears with a dollar figure next to it, that's your sublimit. Common sublimits run from $500 to a few thousand dollars, but this varies by carrier. If the line item is absent, towing is almost certainly not included.
Do not assume towing is bundled into "Comprehensive" or "Physical Damage" coverage. Those sections pay for damage to the boat itself, not for the cost of a tow vessel coming to your rescue.
Step 2: Understand What "Towing and Assistance" Usually Includes
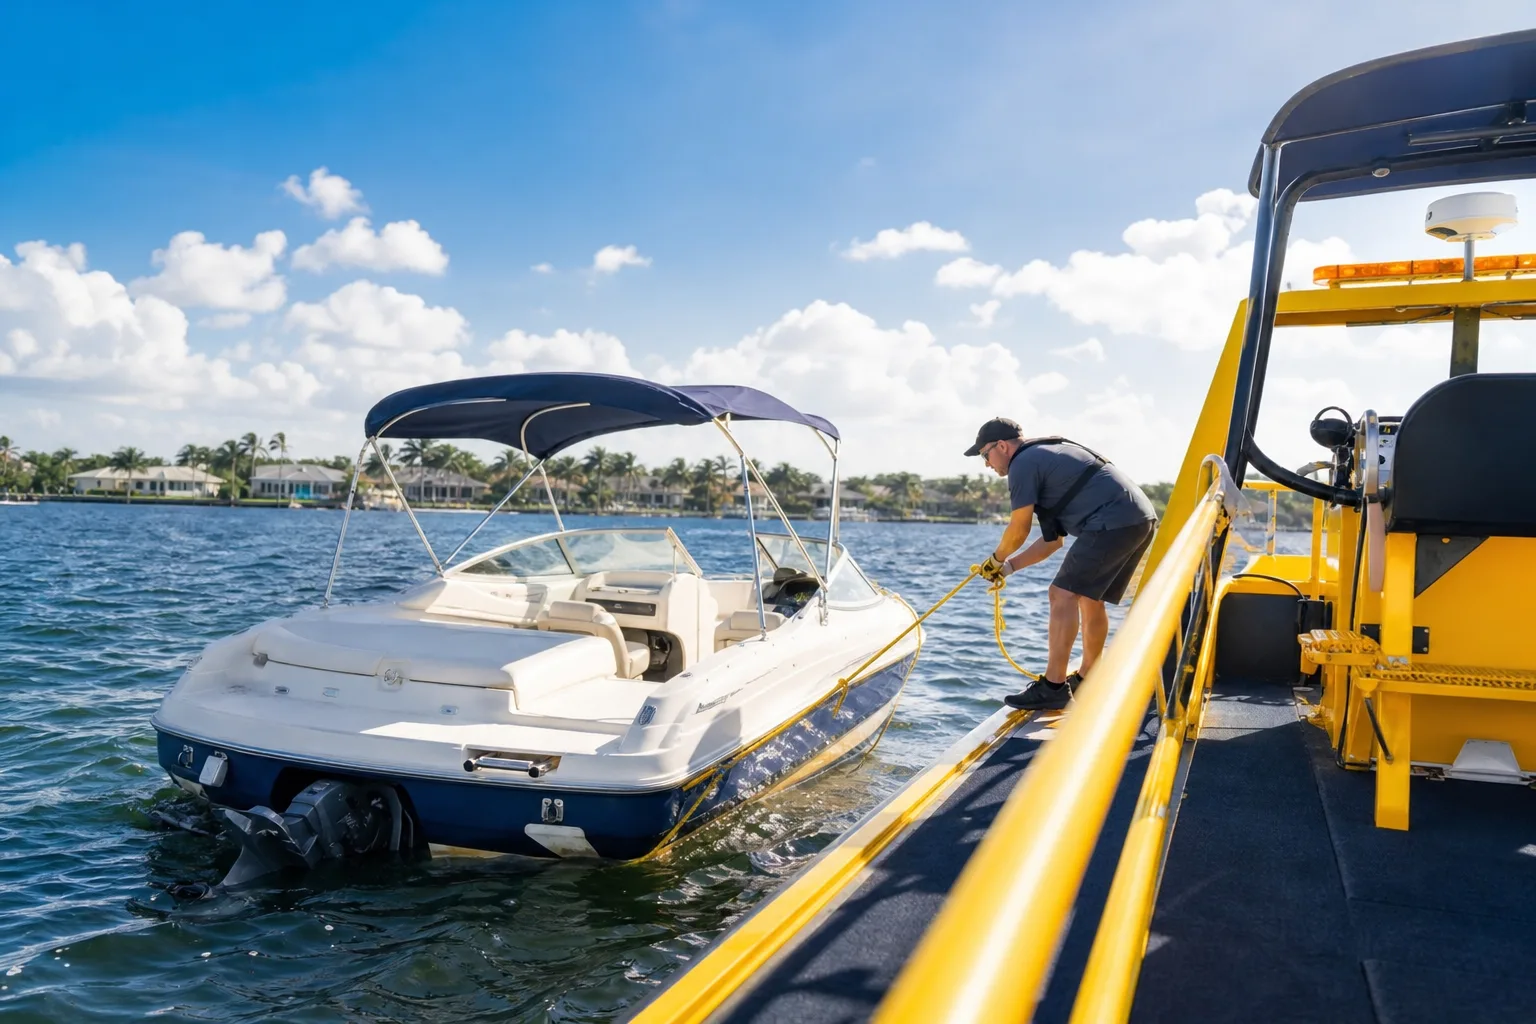
When a policy does include this coverage, it typically pays for:
- A tow back to the nearest safe harbor when the vessel breaks down
- Jump-starts for a dead battery
- Fuel delivery (though you reimburse the cost of the fuel itself)
- Minor on-water repairs needed to get you moving
- Soft ungroundings in some cases
Hard ungroundings, salvage operations after a serious grounding, and wreck removal are usually separate coverage items entirely. The Insurance Information Institute notes that salvage costs can be substantial and are worth confirming independently on your policy.
Step 3: Identify Your Policy's Geographic Limits
Many towing endorsements have a navigation territory. A Florida policy might cover towing within intracoastal or coastal waters up to a certain number of miles offshore, then exclude or restrict coverage beyond that point. If you take your boat to the Bahamas or run offshore trips in the Gulf Stream, check whether your towing benefit extends there or stops at the three-mile territorial boundary.
Cover your boat, yacht, or jet ski the right way. Get a boat quote
Step 4: Compare What a Towing Membership Adds
A membership with a boat towing club is not insurance. It's a service contract. The practical difference matters:
| Feature | Insurance Towing Endorsement | Towing Membership |
|---|---|---|
| Pays for tow cost | Yes, up to sublimit | Yes, typically unlimited tows |
| Covers fuel reimbursement | Often partial | Often included |
| Covers soft ungrounding | Sometimes | Usually yes |
| Covers hard salvage | Rarely | No |
| Counts against a claim | Yes | No |
| Works outside navigation zone | Check policy | Check membership area |
One key point: using your insurance towing benefit typically triggers a claim record, which can affect future renewals. A membership tow does not. Many Florida boaters carry both, using the membership for routine breakdowns and the insurance for larger salvage situations.
Step 5: Ask About Salvage Coverage Separately
Salvage is not the same as towing. If your vessel sinks at the dock, runs aground hard, or is severely damaged in a storm, removing it from the water can cost tens of thousands of dollars. Florida law requires removal of sunken or derelict vessels, and the owner may be held responsible for that cost, confirm the applicable requirement with a licensed agent or attorney.
Check whether your policy includes a salvage or wreck-removal sublimit. If it doesn't, ask your agent whether an endorsement is available.
Step 6: Know When to Call Your Agent vs. the Tow Service
If you're on the water right now and need a tow, call BoatUS, Sea Tow, or the Coast Guard depending on urgency, and sort out the insurance paperwork afterward. If you're at the dock planning your next season, that's the right time to review your declarations page with an agent and close any gaps before they matter.
Common Mistakes
- Assuming homeowners covers a tow. Your homeowners insurance does not extend to on-water assistance. It may cover your boat for certain perils while stored at home, but it won't dispatch a tow vessel.
- Ignoring the sublimit. A $500 towing sublimit sounds fine until a longer offshore tow runs $1,200. Know the cap.
- Skipping the navigation territory clause. Running outside your policy's covered waters can void both your towing benefit and your hull coverage.
- Conflating salvage and towing. They are billed separately, covered separately, and priced very differently.
- Not updating the policy after upgrading the boat. If your vessel's value has changed, your coverage limits, including towing sublimits sometimes tied to hull value, may no longer be adequate.
Bottom Line
On-water towing coverage is a policy-by-policy variable in Florida. Check your declarations page for the line item and sublimit, confirm the navigation territory, and decide whether a towing membership fills the gaps that an insurance endorsement leaves. For salvage and wreck removal, verify that coverage exists and at what limit before hurricane season.
If you want a second set of eyes on your current boat insurance policy or want to compare options from multiple carriers, the team at B & B Insurance Agency is happy to walk through your declarations page with you.
Cover your boat, yacht, or jet ski the right way.
Florida marine coverage from an independent agency that lives on the water too. Tell us what you ride.
Frequently asked questions
Does the U.S. Coast Guard charge for a rescue tow in Florida?
The Coast Guard does not charge for search and rescue operations, but they focus on life-safety situations rather than routine breakdowns. For a mechanical breakdown where no one is in danger, they will typically refer you to a commercial tow service. That commercial tow is where your insurance endorsement or membership comes in.
Can I add a towing endorsement mid-policy if I forgot to include it at renewal?
Most carriers allow mid-term endorsement additions, though the change typically takes effect on the date added, not retroactively. Contact your agent as soon as you realize the gap. It's a straightforward addition for most standard boat policies.
Is my personal watercraft (jet ski) covered under the same towing endorsement as my boat?
Not automatically. A jet ski or personal watercraft is usually a separate insured item, and its towing benefit, if any, is listed on its own line. Check the declarations for each watercraft individually, or ask your agent about a combined policy option.
What happens if I'm towed by a Good Samaritan instead of a licensed tow service?
Insurance towing benefits are generally designed to reimburse costs from commercial towing operators. A tow from a fellow boater typically involves no charge, so there's nothing for the policy to reimburse. However, if the assisting vessel damages your boat in the process, that's a different coverage question involving liability and hull damage.
This article is general information, not legal or financial advice. Coverage depends on the terms, conditions, and exclusions of your specific policy, so talk with a licensed insurance agent about your situation.
Related Coverage from B & B
Have a question about this topic?
Our experienced agents are happy to help — no pressure, just straight answers.


